
Key takeaways
What this article covers, in order:
- Key takeaways
- Why retail reconciliation gets messy fast
- What makes Stripe, Square, and bank deposits hard to match?
- How does AI bookkeeping help with Stripe and Square reconciliation?
- What is the fastest way to reconcile Stripe, Square, and bank deposits?
- Common Stripe and Square scenarios retail owners should expect
AI bookkeeping for small business helps retail owners match card payouts, fees, refunds, and bank deposits without doing every line by hand. In the United States, that matters most when Stripe or Square batches transactions in ways that do not neatly match what lands in your bank account.
Key takeaways
- Retail deposits often differ from daily sales because of processor fees, refunds, tips, chargebacks, and payout timing.
- AI bookkeeping can speed up matching Stripe, Square, and bank deposits by grouping transactions into the right payout batches.
- A clean workflow starts with three records: sales activity, processor payouts, and actual bank deposits.
- Faster reconciliation improves cash visibility, month-end close, and confidence in your financial reports.
- Small retailers using spreadsheets or legacy workflows can reduce manual review with AI bookkeeping and better bank matching rules.
Why retail reconciliation gets messy fast
Retail businesses in the United States rarely receive one bank deposit for one sale. Instead, card processors collect many transactions, subtract fees or adjustments, and send batch payouts on their own schedule. That is why your point-of-sale totals, payment processor dashboard, and bank statement often show different numbers on the same day.
A boutique in Chicago might sell $4,800 on Friday. But the bank may receive $4,621.40 on Monday. The difference may include card processing fees, a refunded order, and a delayed payout cutoff. If you book only the bank deposit, revenue can be understated. If you book only gross sales, cash will not tie out.
This is where ai bookkeeping for small business becomes practical, not theoretical. The goal is not to replace your review. The goal is to reduce the time spent hunting for the reason a $4,621.40 deposit does not match the sales report.
The three records you need to reconcile
For most retail businesses, reconciliation works best when you separate these records:
- Gross sales activity This includes sales, discounts, sales tax collected, tips if applicable, and refunds.
- Processor activity This includes Stripe or Square fees, chargebacks, reserve movements, and payout batch details.
- Bank activity This is the actual deposit amount that reached your checking account.
When these are mixed together in one journal entry, errors are harder to spot. When they are separated clearly, your books tell a cleaner story.
What makes Stripe, Square, and bank deposits hard to match?
Stripe and Square do not always pay out on the exact day of sale. They may combine multiple sales into one transfer. They may also reduce a payout for fees, disputes, or refunds. Your bank then shows only the net amount received.
That creates four common problems:
1. Net deposits hide the fee detail
If your bank shows a deposit of $2,910, that number may already be net of processing fees. You still need the gross sales and fee expense recorded correctly.
2. Refunds may happen after the original sale
A customer may return an item three days later. The processor might subtract that refund from a future payout, not the original one.
3. Sales tax collected is not revenue
Retailers collect state and local sales tax from customers. That amount is generally a liability until remitted, not income. This is general information, not tax or legal advice.
4. Payout timing crosses month-end
A sale on 03/31/2026 may not hit the bank until 04/02/2026. If you book cash only when the deposit arrives, March revenue may be incomplete.
These issues are normal. The fix is to reconcile by payout logic, not by guessing from bank deposits alone.
How does AI bookkeeping help with Stripe and Square reconciliation?
AI bookkeeping helps by identifying likely matches between processor payouts, sales records, and bank deposits. It can group related transactions, flag exceptions, and suggest entries so you review fewer lines manually.
Under that simple idea, the biggest benefit is speed with control. A good workflow uses ai-powered matching to connect one bank deposit with the right payout batch instead of forcing you to compare every transaction by hand.
What AI is actually doing in the workflow
An ai tool in bookkeeping is most useful when it handles pattern recognition. In retail, those patterns include:
- Repeated payout amounts and timing
- Common fee structures
- Normal refund behavior
- Deposits that land one or two business days after sales
- Differences between gross sales and net cash received
For example, if Square usually deposits the prior day’s card sales minus fees, the system can learn that pattern. If Stripe sends grouped payouts every weekday, the software can look for that relationship first. You still review exceptions. But you no longer start from a blank screen.
Where human review still matters
AI can speed up matching, but it should not blindly post everything. A person should still review:
- Large refunds
- Unusual chargebacks
- Duplicate deposits
- Month-end cutoff issues
- Sales tax liability mapping
- Transfers between accounts
That is why many small businesses want AI accounting software that shortens the work without removing oversight.
What is the fastest way to reconcile Stripe, Square, and bank deposits?
Use a payout-based workflow. Record gross sales and processor fees separately, then match each payout to the bank deposit. Review only exceptions like refunds, chargebacks, and timing differences.
The fastest method is not to reconcile each sale to the bank. It is to reconcile each payout batch to the bank, then tie the underlying sales to that payout. This cuts the number of comparisons dramatically.
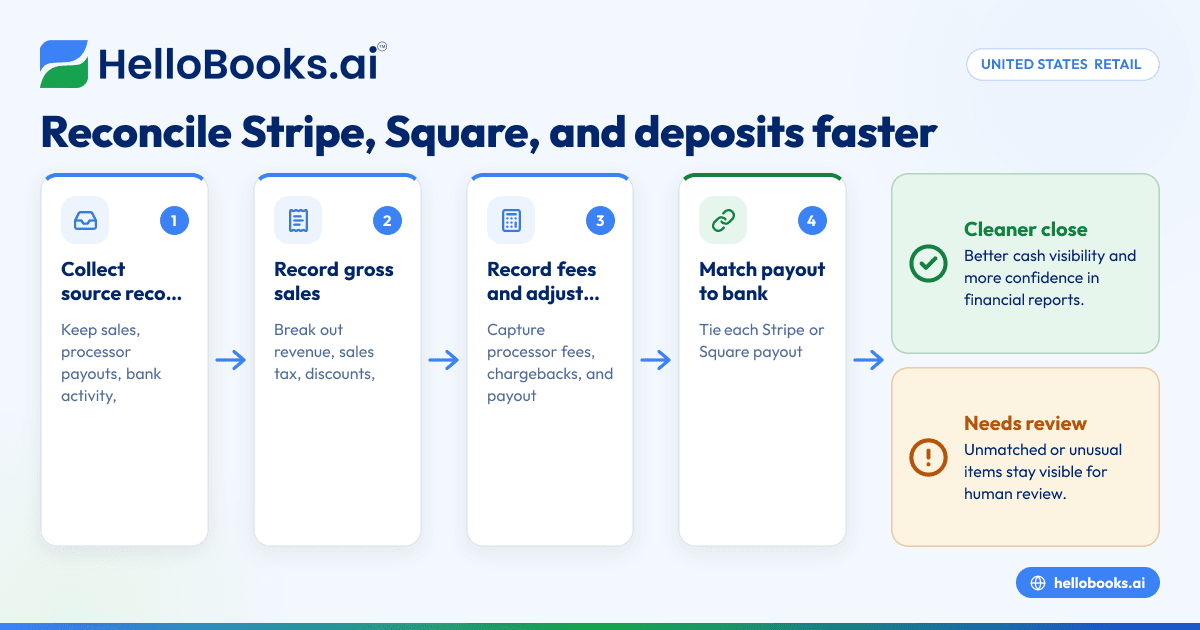
A simple 5-step retail reconciliation workflow
1. Import or collect the right source data
Start with:
- Your daily sales summary
- Stripe or Square payout report
- Bank feed or bank statement
- Refund and dispute activity
If you use spreadsheets, keep each source in a separate tab. Do not combine them too early.
2. Record gross sales first
Book daily or batch sales at gross value. Break out:
- Product revenue
- Sales tax collected
- Discounts
- Tips, if relevant
- Refunds, if already known
This gives you a true revenue record before processor deductions.
3. Record processor fees and adjustments
Next, record fees, refunds deducted from payouts, and chargebacks. This shows why net cash is lower than gross sales.
4. Match the payout batch to the bank deposit
Now compare the processor’s payout amount to the bank deposit. In most cases, the bank should match the processor payout exactly, even if it does not match sales totals.
5. Review exceptions and close the period
Look at unmatched items, deposits in transit, month-end timing gaps, and duplicate entries. Then lock the period once the cash and processor balances make sense.
Why this method works better than matching from the bank alone
Bank-only reconciliation misses context. The bank shows cash received. It does not explain gross sales, fees, or customer refunds. A payout-based method preserves that detail.
For a Houston retail store, this can mean the difference between seeing “deposit received” and seeing “$3,250 gross sales, $118 fees, $42 refund, $3,090 net payout.” That is the level of detail you need for clean books.
Common Stripe and Square scenarios retail owners should expect
Retail reconciliation gets easier when you know which mismatches are normal.
Same-day sales, next-day deposits
Many processors deposit on a delay. That means Friday sales may hit the bank on Monday. This is not an error. It is a timing difference.
One deposit covers multiple days
Holiday weekends and processor cutoff times can create a payout that includes more than one day of sales. If you reconcile by date only, this looks wrong. If you reconcile by payout ID or processor batch, it usually makes sense.
Refunds reduce a future payout
A refund processed today may lower tomorrow’s deposit. If the refund was already booked in sales activity, be careful not to count it twice.
Chargebacks and disputes
These often create separate deductions that are easy to miss on the bank feed. They should be reviewed carefully because they can affect revenue, fees, and cash.
Sales tax in the deposit flow
If your daily sales report includes sales tax collected, that amount should generally be separated from revenue. Reconciliation is not only about matching cash. It is also about proper classification.
Where small retailers lose time in manual bookkeeping
Manual reconciliation usually breaks down in a few predictable places.
Too much work happens in spreadsheets
Spreadsheets are flexible, but they rely on perfect exports, formulas, and copy-paste habits. One broken formula can throw off an entire month.
Staff book net deposits as revenue
This is one of the most common shortcuts. It saves time today but creates reporting problems later. Fees disappear into revenue, and sales tax may be handled incorrectly.
Month-end review starts too late
If unmatched deposits build up for weeks, cleanup becomes harder. Retail books are easier to manage with frequent review.
Systems do not talk to each other
Sales data, processor data, and bank data often live in separate places. That is where ai automation helps most. It reduces the need to compare files line by line and helps surface the few items that need attention.
What should you check before trusting AI bookkeeping software?
Check whether it supports payout matching, fee separation, refund handling, and bank reconciliation with a clear audit trail. You should be able to see why a match was suggested and edit it before finalizing.
That short list matters because speed without visibility can create new errors. Good software should help you review faster, not hide the accounting logic.
A practical evaluation checklist
If you are comparing tools, ask:
- Can it separate gross sales from net bank deposits?
- Can it match one payout to one bank deposit?
- Can it handle refunds and chargebacks cleanly?
- Can you review suggested matches before posting?
- Does it keep a clear history of changes?
- Can it support your accountant at month-end?
Many retail businesses start here when looking for accounting software in the USA or a QuickBooks alternative that reduces manual cleanup.
A real-world example for a U.S. retail business
Imagine a gift store in Detroit using Square for in-store payments and Stripe for online orders.
On 06/14/2026, the business has:
- Square gross sales: $2,400
- Stripe gross sales: $1,200
- Sales tax collected across both: $216
- Total processor fees: $98
- One refund: $75
The owner might expect $3,600 in the bank. But that is not what happens.
A cleaner view is:
- Gross sales recorded by channel
- Sales tax separated as a liability
- Fees recorded as processing expense
- Refund recorded against sales or returns
- Net payouts matched to separate bank deposits from Square and Stripe
If Square deposits $2,280 and Stripe deposits $931, those deposits may both be correct based on timing and deductions. The job of bookkeeping is to explain the numbers clearly.
With an ai software workflow, the system can suggest those matches based on payout dates, expected fee patterns, and historical settlement timing. The owner or accountant then reviews the exceptions instead of rebuilding the story from scratch.
How often should a retail business reconcile deposits?
Daily review is ideal for high-volume retail, but weekly is often enough for many small businesses. Monthly-only reconciliation is usually too slow because errors stack up and are harder to explain.
A practical cadence by business type
- High transaction retail: daily or every other day
- Small shop with moderate volume: weekly
- Multi-location business: near-daily for deposits, weekly for exceptions
- Month-end close: final review of timing differences and open items
The faster you reconcile, the easier cash management becomes. You also get more reliable profit reporting and a smoother year-end process for your accountant.
If you still handle deposit matching manually, software focused on bank reconciliation software and expense-management software can help reduce the end-of-month scramble.
Signs your current process is too manual
You do not need perfect books to know the workflow is strained. Watch for these signs:
- Unexplained processor clearing balances
- Frequent “plug” entries to force reconciliation
- Fees posted in lump sums without backup
- Refunds showing up twice
- Bank deposits matched to the wrong sales days
- Delays closing the month by more than a few days
These are process issues, not just bookkeeping issues. They usually signal that the business has outgrown a spreadsheet-first approach.
When to change your workflow or software
Most retail businesses should reconsider their process when transaction volume rises, channels multiply, or reporting needs become more serious.
That often happens when:
- You add ecommerce to a physical store
- You open a second location
- You need cleaner statements for a lender
- Your accountant spends too much time on cleanup
- You want better visibility into fees and margins by channel
At that point, using accounting software for small business can be less about automation for its own sake and more about getting dependable numbers each week.
If your team wants a simpler way to reconcile sales, payouts, and bank deposits, HelloBooks can help streamline the work and reduce manual review. You can book a demo to see the workflow or compare options on the pricing page.
Frequently asked questions
Is it okay to book Stripe or Square deposits as sales?
Usually, no. A bank deposit is often net of fees, refunds, or other adjustments. Booking the net deposit as revenue can understate sales and hide processing costs.
Do I need to reconcile every individual retail transaction?
Not usually for bank reconciliation. Most retail businesses reconcile processor payout batches to bank deposits, then tie sales activity to those batches. That approach is faster and usually cleaner.
How often should sales tax be reviewed during reconciliation?
Review it as part of your normal reconciliation process, especially when sales are high or you sell across multiple jurisdictions. Make sure tax collected is separated from revenue in your books.
Can AI fully automate retail bookkeeping?
It can automate parts of the workflow, but review still matters. Exceptions like chargebacks, duplicate entries, and unusual refunds should be checked by a person before finalizing records.
What is the main benefit of AI bookkeeping for small business retailers?
The biggest benefit is time saved on repetitive matching work. It also improves consistency, so your books are easier to trust at month-end and during tax season.