
Key takeaways
What this article covers, in order:
- GST Treatment of Vendor Prepayments and Customer Advances
- Introduction
- Key concepts and definitions
- Types of prepayments and advances
- Time of supply basics
- Invoice and receipt interactions
GST Treatment of Vendor Prepayments and Customer Advances
Introduction
Prepayments, advances and GST — Understanding how GST works with prepayments & advances can prevent tax errors. GST applicability on vendor prepayments and customer advances: this article focuses on the points when GST arises when vendor prepayments / customer advances are made. It explains invoice, timing and credit rules simply and pragmatically. The instructions are written in plain language and actionable steps you can implement in everyday accounting.
Key concepts and definitions
A prepayment is an advance payment for goods or services. Advance is a sum of money paid in advance to the supplier by a customer before delivery takes place. Delivery time refers to the time at which GST is due to the tax authority. Input tax credit refers to the tax that a registered buyer can reclaim when they are receiving taxable supplies.
Types of prepayments and advances
- Deposit taken as security
- Payment for work in progress
- Prepayment in full for delivery in the future
It is usually in the form of vendor prepayments and customer advances. Both forms can trigger GST but they are at different times based on invoice and receipt. This explains how one can determine when to include GST on the amount.
Time of supply basics
The time of supply rules determine when GST is payable on a payment or invoice. In the case of prepayments, the time of supply is determined when payment is received or an invoice is issued — whichever comes first. This rule ensures collection of GST at the earliest taxable event. To meet reporting deadlines, sellers need to carefully track receipts and invoices.
Invoice and receipt interactions
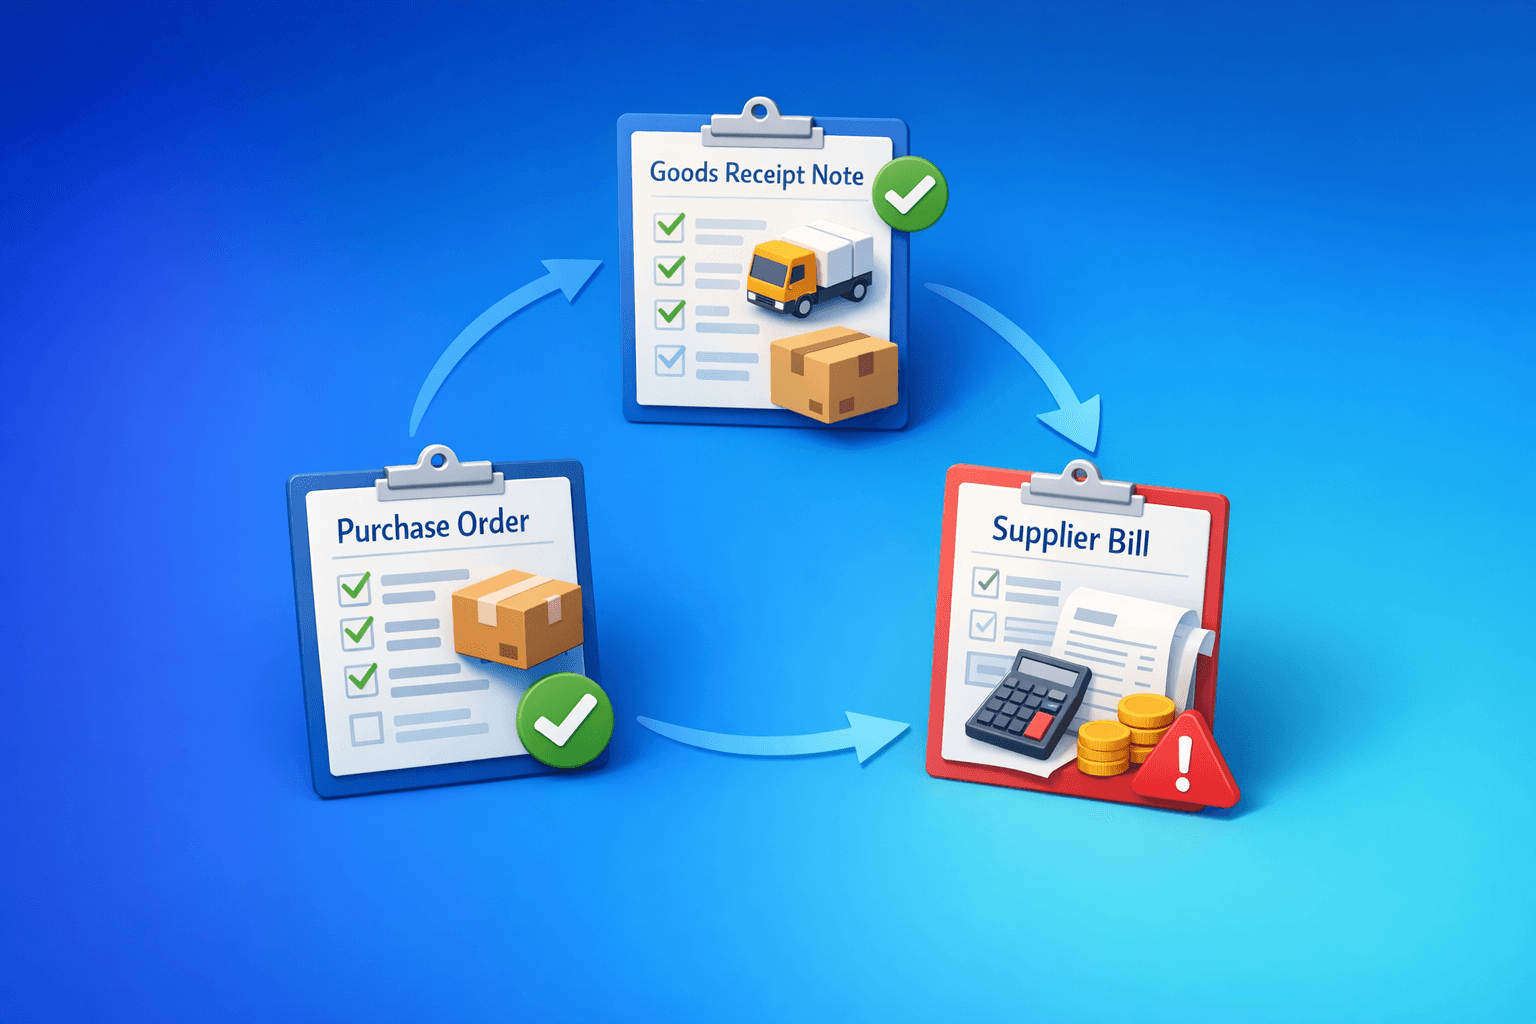
If a vendor issues an invoice before supply, the invoice date may determine the time of supply. Receipt of payment before the invoice is issued by a seller may trigger time of supply based on the date the receipt is received. Accurate records must match receipts and invoices, which is what tax authorities expect. You will need to reconcile these dates in your accounting system every tax period.
GST on customer advances
When a commercial entity gets an advance of delivery from the customer, GST shall be applied on such advance immediately. The seller must treat the advance as consideration for a future taxable supply and furnish a tax invoice or receipt documenting the tax portion of that advance. Reporting the tax for the correct period avoids penalties and interest.
GST on vendor prepayments
When a vendor receives money in advance from the buyer, it is essential for the vendor to ascertain when the GST on goods will be payable. Without a valid tax invoice issued by the vendor, buyers cannot avail input tax credit. Receipts with tax information can, in certain situations, support a credit claim. When buyers perform prepayments, they should request proper documentation.
Input tax credit conditions
- Claims must be in registered recipient status
- Must receive a tax invoice or proper tax document
- Must use the goods or services in a taxable activity
Conditions for claiming input tax credits must be fulfilled by buyers. The simple payment does not entitle a credit in the absence of required documents and taxable use. Buyers must also ensure their claim aligns with the seller's accounting for GST on an advance. Keep documentation supporting every statement and claim in case of audit.
Adjustments and refunds
If no supply takes place after an advance, parties are required to reverse the GST paid earlier. The refund of the advance may be accompanied by an adjustment reversing the GST declared earlier. Both buyer and seller need to issue corrected tax documents that reflect the reversal. Follow formal adjustment procedures to avoid disputes and ensure proper tax treatment.
Record keeping and examples
- Save receipts with tax amounts and dates
- Keep invoices and adjustment notes for every advance
- Monthly reconciliation of advance accounts with returns
There are many such examples; let us pick a couple. Example 1: The buyer makes full advance payment and the vendor raises an invoice immediately. The vendor shall mention the GST in his return for that period, and the buyer can claim input tax credit as soon as he gets the valid invoice. Example 2: When a partial advance is paid without an invoice being issued, in most instances the vendor must still account for GST upon receipt. Both examples show the importance of timely invoicing and correct records.
Practical compliance tips
- When paying, demand tax invoices
- File returns after matching receipts and invoices
- Maintain a clear advance tracking worksheet for each project
Train staff to check accounting for advances and prepayments. Simple checklists can be used to confirm that invoices accompany receipts. Review supplier contracts to address when tax will be charged and invoiced. These measures help eliminate mistakes and minimize audit risk.
Common pitfalls to avoid
Claiming input credit based on an ineligible tax document is a common mistake. Another is non-payment of GST on receipt of an advance. Many do not issue adjustment notes when advances are refunded or cancelled. Preempt these issues with proper record keeping and timely invoicing.
Conclusion
Vendor prepayments and customer advances can give rise to the payment of GST at an early stage in a transaction lifecycle. Sellers and buyers need to be careful about when to apply the tax based on time of supply, invoice rules, and document requirements. Maintaining clear records, timely invoices and routine reconciliations are practical ways to minimize tax risk and facilitate reporting. Put these controls in place to reduce exposure and support accurate GST reporting.