


Key takeaways
What this article covers, in order:
- Key takeaways
- What are sales tax journal entries in the United States?
- How do you record sales tax at the time of sale?
- What is the basic sales tax journal entry formula?
- How do you record a payment to the state?
- Common sales tax journal entries small businesses need
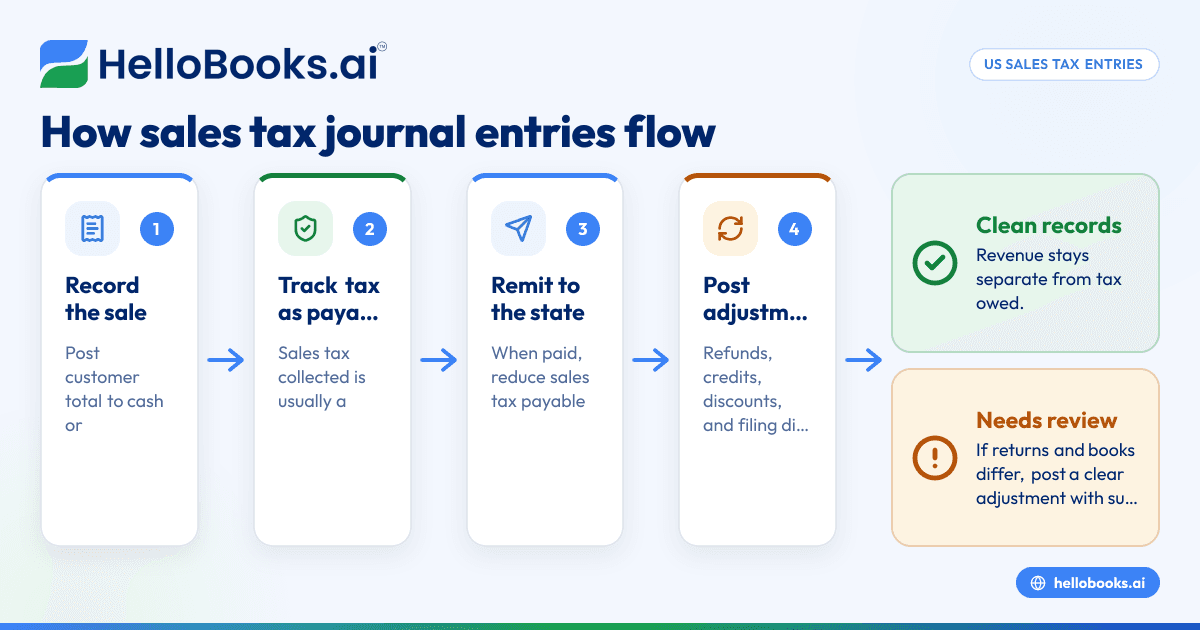
Sales tax journal entries in the United States record two separate things: revenue you earned and sales tax you collected on behalf of a state or local tax authority. In most cases, sales tax is not your income. It is a liability until you remit it.
If your books are messy, the fix is usually simple. You need a clear process for recording tax at the time of sale, tracking payments to the state, and posting adjustments for discounts, refunds, vendor credits, or filing differences.
Key takeaways
- Sales tax collected is usually booked to a liability account, not revenue.
- The basic entry at sale is debit cash or accounts receivable, credit sales, and credit sales tax payable.
- When you remit tax, you debit sales tax payable and credit cash.
- Refunds, credit memos, and discounts can change the tax due and should be posted with matching entries.
- A monthly reconciliation between your books, point-of-sale or billing system, and filed returns helps catch errors early.
- If you want less manual work, AI bookkeeping tools can help automate categorization and review.
What are sales tax journal entries in the United States?
Sales tax journal entries in the United States are the accounting entries used to record tax collected from customers, tax paid back to a state or local authority, and later corrections. They matter because your profit and loss should show sales revenue, while your balance sheet should show the tax you still owe.
For most small businesses, sales tax accounting has three moving parts:
- The original sale.
- The payment to the tax authority.
- Any change after the sale, such as a refund, credit, or filing adjustment.
This sounds simple, but many small businesses mix sales tax into revenue. That creates two problems. First, revenue gets overstated. Second, your liability account does not match what you actually owe.
A cleaner chart of accounts helps. Many businesses use accounts like these:
- Sales revenue
- Sales tax payable
- Accounts receivable
- Cash
- Sales returns and allowances
- Discounts or contra revenue
- Sales tax expense or prior-period adjustment, only when needed
If you sell in more than one state or local jurisdiction, you may also track sales tax payable by state. That gives your controller, bookkeeper, or outside accountant a clearer audit trail.
How do you record sales tax at the time of sale?
Record the full amount billed to the customer as cash or receivables, the pre-tax amount as revenue, and the tax as a liability. That keeps your income statement clean and shows what you owe for unremitted sales tax.
Here is the standard journal entry for a taxable sale.
Example: Cash sale
A retail store in Chicago sells goods for $1,000 and charges $80 in sales tax.
Journal entry:
- Debit Cash $1,080
- Credit Sales Revenue $1,000
- Credit Sales Tax Payable $80
The business earned $1,000. It collected $80 for the tax authority. That $80 is not revenue.
Example: Credit sale
A wholesaler in Houston invoices a customer for $5,000 plus $412 in sales tax.
Journal entry:
- Debit Accounts Receivable $5,412
- Credit Sales Revenue $5,000
- Credit Sales Tax Payable $412
The same logic applies whether you collect payment now or later.
What if shipping is involved?
If shipping is taxable in your state and on that transaction, include the taxable shipping amount in the sales tax calculation. If shipping is not taxable, keep it separate. The accounting entry still follows the same pattern: taxable charges drive the tax liability.
Because state and local rules differ, confirm taxability for your business and location with your accountant or state guidance. This article is general information, not tax or legal advice.
What is the basic sales tax journal entry formula?
The formula is simple: debit cash or accounts receivable for the total invoice, credit revenue for the pre-tax sale, and credit sales tax payable for the tax collected. When you send the money to the state, reverse the liability with a debit to sales tax payable and a credit to cash.
That formula works for most retail, ecommerce, and service transactions where you collect sales tax from a customer. It also works whether your books are in spreadsheets, QuickBooks, or a newer AI accounting software workflow.
A practical way to think about it is this:
- Customer total goes to cash or receivables.
- Your earnings go to revenue.
- Tax you are holding goes to a payable account.
If you use a point-of-sale system, ecommerce platform, or billing tool, the system may create summary entries automatically. Even then, you still need to confirm that sales tax is landing in a liability account and not being mixed into income.
Simple formula
For a taxable sale:
Debit Cash or Accounts Receivable = pre-tax amount + sales tax
Credit Revenue = pre-tax amount
Credit Sales Tax Payable = sales tax collected
For a remittance:
Debit Sales Tax Payable = amount paid
Credit Cash = amount paid
How do you record a payment to the state?
Debit sales tax payable and credit cash for the amount remitted. If your books are correct, that entry reduces the liability already built up from your taxable sales.
Example: Remitting the tax
Your business has a sales tax payable balance of $3,450 for the filing period. You submit the payment.
Journal entry:
- Debit Sales Tax Payable $3,450
- Credit Cash $3,450
After the entry, the liability for that filing period should be reduced by the payment amount.
When the filed return does not match the books
This is common. Your filed return may differ from the general ledger because of rounding, exemptions, timing, marketplace facilitator activity, or late credit memos.
If the difference is small and clearly identified, record an adjustment. For example:
- If the filed amount is higher than your books, you may need to increase sales tax payable.
- If the filed amount is lower than your books, you may need to reduce sales tax payable.
Keep the adjustment account clear. Many businesses use a temporary account like “sales tax adjustments” and then review it monthly. Do not hide differences in revenue unless the issue truly came from revenue recognition.
Common sales tax journal entries small businesses need
The basic sale and payment entries cover most activity. But real businesses also issue refunds, apply discounts, write off bad debts, and discover prior-period mistakes.
1. Customer refund on a taxable sale
Suppose a Detroit shop refunds a prior sale of $200 plus $16 sales tax.
Journal entry:
- Debit Sales Returns and Allowances $200
- Debit Sales Tax Payable $16
- Credit Cash $216
This reduces both revenue and the tax liability, assuming the refund reduces the tax you owe under the rules that apply to that transaction.
2. Credit memo for a billed customer
A customer disputes part of a $1,000 taxable invoice and receives a $100 credit plus $8 related tax.
Journal entry:
- Debit Sales Returns and Allowances $100
- Debit Sales Tax Payable $8
- Credit Accounts Receivable $108
3. Early payment discount
If you reduce the amount owed by the customer and the tax treatment changes with that discount, record the discount and the tax effect together. The exact treatment depends on the facts and the jurisdiction, so review your sales tax settings and filing logic carefully.
A typical entry may include:
- Debit Sales Discounts
- Debit Sales Tax Payable for the tax reduction, if applicable
- Credit Accounts Receivable
4. Bad debt
In some cases, bad debt may affect sales tax reporting. Whether and when you can reduce tax previously remitted depends on state rules. The accounting may involve bad debt expense and a related sales tax adjustment, but only if supported by the applicable rules and filing treatment.
5. Prior-period correction
If you discover that last month’s sales tax collected was understated by $250 because a taxable sale was coded as exempt, you may post:
- Debit Sales Tax Adjustment Expense $250
- Credit Sales Tax Payable $250
If the error also affected revenue, fix both sides. Document the reason and tie it to the amended return or next filing.
Cash basis vs accrual basis: does the entry change?
The journal entry structure often stays the same for the sale itself, but the timing in your books may differ based on how you record revenue and receivables. Sales tax filing requirements and accounting method do not always line up, so do not assume your income tax method answers your sales tax bookkeeping questions.
On an accrual basis, you usually record the sale and tax when the invoice is issued or the sale occurs. On a cash basis, many small businesses record the activity when cash is received. Still, the key principle remains: tax collected is generally a liability, not income.
This is why monthly review matters. A business can be cash basis for some reports and still need accurate liability tracking for sales tax. If your systems are spread across Stripe, a point-of-sale app, and spreadsheets, reconciliation becomes even more important.
How should ecommerce and marketplace sales be posted?
Post direct sales where you collect tax using the standard revenue-plus-liability entry. For marketplace sales, review the settlement reports carefully because in many cases the marketplace may collect and remit certain tax amounts, which changes what should hit your payable account.
The accounting challenge with ecommerce is usually not the entry itself. It is understanding who collected the tax and where the cash settled.
Direct website sales
If your own store charges the customer and you collect the tax, the entry usually looks like this:
- Debit Cash or Clearing Account for total customer payment
- Credit Sales Revenue for the pre-tax sale
- Credit Sales Tax Payable for tax collected
If processor fees are netted from deposits, book those separately. Do not reduce revenue just because the bank deposit is lower than the gross sale.
Marketplace sales
For marketplace transactions, the platform’s reports often show gross sales, fees, tax collected, and net payout. The right journal entry depends on what the marketplace collected and remitted versus what you remain responsible for.
This is where many businesses create duplicate tax liabilities by mistake. They credit sales tax payable even though the marketplace already handled the collection and remittance. Review the settlement report fields and your filing process before posting summary entries.
How do you adjust sales tax for discounts, rounding, and corrections?
Post adjustments to the sales tax payable account when the correction changes the tax you owe. Use a separate adjustment or contra account when needed so you can trace why the filed return differs from your original sales entries.
A clean adjustment process has three steps:
- Identify the reason for the difference.
- Determine whether the issue changes revenue, tax liability, or both.
- Post the smallest clear entry that fixes the books and can be explained later.
Typical adjustment sources
- Invoice discounts
- Refunds after filing
- Tax-exempt customers coded incorrectly
- Product taxability errors
- Rounding differences
- Processor or platform mapping problems
- Journal entries posted to revenue instead of liability
Keep support for every adjustment. Save the credit memo, exemption document, amended invoice, or filing workpaper. If an auditor or buyer asks questions later, that backup matters.
Use one review schedule
Many small businesses wait until return time to fix everything. That creates rushed work and old errors. A better approach is to review weekly for high-volume sellers and monthly for lower volume businesses.
If your team wants fewer manual checks, bank reconciliation software and expense management software can help clean up adjacent parts of the month-end close so sales tax review is easier.
Monthly sales tax reconciliation process
Reconciliation is what turns journal entries into reliable numbers. Without it, your payable account can drift for months.
Step 1: Pull the sales detail
Export taxable and exempt sales by period from your billing, POS, or ecommerce system. Include gross sales, tax collected, refunds, and credits.
Step 2: Tie totals to the general ledger
Match total sales and tax to the revenue and sales tax payable accounts. Investigate every material difference.
Step 3: Compare to the draft or filed return
Your books should support the taxable sales and tax due on the return. If they do not, identify whether the issue is timing, coding, or a posting error.
Step 4: Post adjustments with support
Do not edit old entries without a trail. Post a current adjustment entry with a memo that explains the reason.
Step 5: Review remittance postings
Confirm that each payment reduced sales tax payable and cleared the bank.
This process is where automation can help. Some businesses are beginning to use ai sales tax workflows to flag unusual tax amounts, missing mappings, or differences between sales system reports and the ledger. That does not replace review, but it can cut manual checking time.
Best practices for small businesses
Good sales tax accounting is mostly about consistency. You do not need a huge finance team to keep it under control.
Use separate accounts
Never bury sales tax inside revenue. Keep a dedicated sales tax payable account, and consider separate subaccounts by state if volume justifies it.
Keep source systems aligned
If your invoicing tool marks an item taxable, your accounting setup should reflect that. Broken mappings are a common cause of bad entries.
Avoid manual netting
Do not post only the net bank deposit from a processor and call it done. Gross sales, fees, refunds, and tax should be visible.
Review exemption handling
If you sell to exempt customers, keep documentation organized and make sure those transactions are coded correctly from the start.
Standardize month-end close
Use a checklist. If your business has outgrown spreadsheets, dedicated accounting software in the USA can reduce manual journal work and improve audit trails.
Know when to get help
If you are filing in multiple states, using marketplaces, or fixing old errors, ask a qualified advisor to review your setup. You can also find an accountant if you need outside support.
When should you automate sales tax bookkeeping?
Automate when transaction volume makes manual review slow, when you sell across multiple channels, or when your payable account stops matching filed returns. The goal is not fewer controls. The goal is better controls with less manual entry.
Automation helps most when your team is doing the same steps every month:
- Importing sales summaries
- Splitting revenue from tax
- Matching deposits
- Posting refunds and credits
- Reconciling liability balances
Read next
This article covers one part of a bigger topic. For the complete picture, read our guide to sales tax.


