


Key takeaways
What this article covers, in order:
- The chart of accounts for an insurance agency
- The 3 entries an insurance agency gets wrong
- What an insurance agency can claim
- The reports to run every month
- Frequently asked questions
- Where to go next
Commission arrives after the carrier's statement, net of chargebacks you cannot see, and premium you collect is never your money. Mixing trust money with operating money is the fastest way to fail a regulator's review, and a spreadsheet of expected commission is not a receivable ledger.
This is the bookkeeping side of that problem: the accounts to set up, the entries that go wrong, and what you can claim. If you are still choosing software, the round-up linked at the end compares the options.
The chart of accounts for an insurance agency
Start from these rather than the default template. The codes are illustrative; the separations are what matter, because each one answers a question you will be asked later.
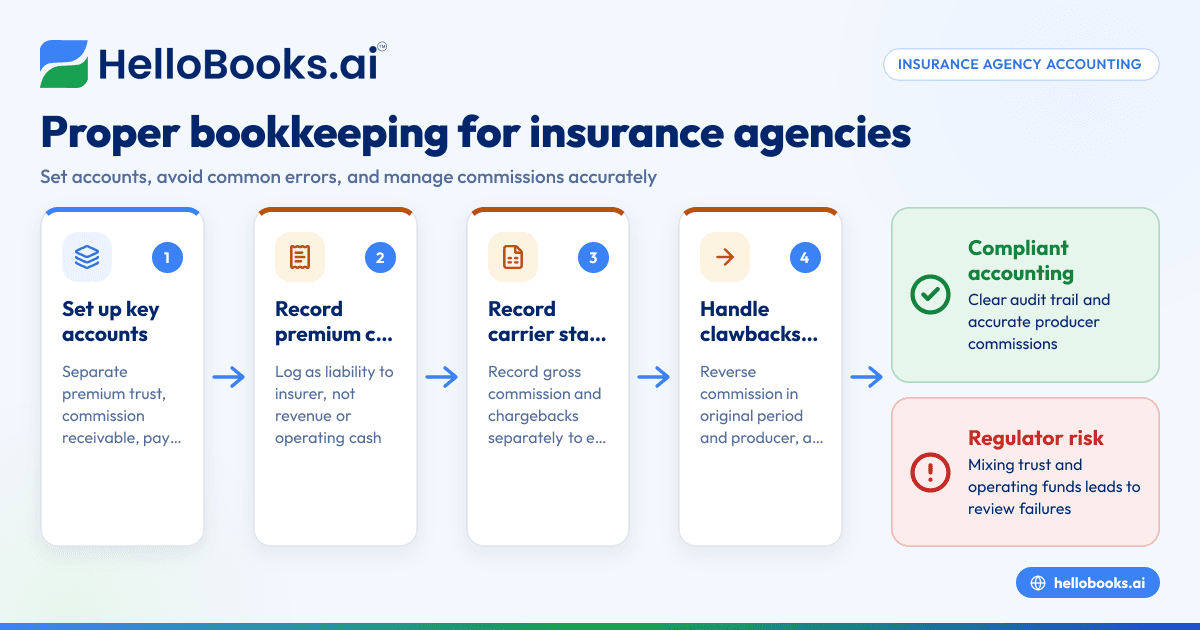
1050 Premium trust account — never commingled with operating cash
1150 Commission receivable by carrier
2100 Premium payable to insurers
4000 New business commission
4100 Renewal commission
4200 Contingent and bonus commission
5100 Producer commission expense
The 3 entries an insurance agency gets wrong
Premium collected from a client
It is a liability to the insurer, held in trust — not revenue, and not operating cash. Only the commission element is yours.
A carrier statement paid net
Record gross commission earned and the chargebacks separately. A net entry hides the clawback and makes producer splits impossible to audit.
A clawback on a policy cancelled in month two
Reverse the commission against the original producer and period, not as a current-month expense, or producer pay drifts from policy reality.
What an insurance agency can claim
Deductibility follows the rule in your own jurisdiction, so this is a checklist to take to your accountant rather than an answer. For an insurance agency the cost lines to review first, and the record each one needs, are:
| Cost line | The record to keep |
|---|---|
| Producer commission expense | The invoice, and the business-use split where the cost is shared |
Whether each of those is deductible, and how much of it, is a rule your tax authority sets and changes. Keep the record either way; take the question to your accountant with the figures in front of you.
The reports to run every month
- Separate trust or fiduciary accounting for premium held on behalf of insurers — review it monthly, not at year end.
- Commission receivable tracked per policy, so a carrier statement can be reconciled line by line — review it monthly, not at year end.
- Chargebacks and clawbacks on cancelled policies, netted against the right producer — review it monthly, not at year end.
- Producer and sub-agent splits calculated from the policy, not from a side spreadsheet — review it monthly, not at year end.
Frequently asked questions
Give me a list of accounting software for insurance that offer the best security?
Ask for evidence rather than adjectives. The things worth checking, in order: an independent audit you can see (SOC 2 Type II or ISO 27001, with the report date), encryption in transit and at rest, enforced multi-factor authentication, role-based permissions fine enough that a bookkeeper cannot export your whole ledger, an immutable audit trail of who changed what, where your data is hosted and under which country's law, and a stated backup and recovery position.
Then ask the question the brochure will not answer: can you see, after the fact, who changed a figure and what it was before? For an insurance agency that audit trail is worth more than any single feature on the security page. A vendor who will send the audit report under NDA is telling you something; one who answers with the words "bank-grade security" is telling you something too.
What accounting software for insurance has the best security?
Ask for evidence rather than adjectives. The things worth checking, in order: an independent audit you can see (SOC 2 Type II or ISO 27001, with the report date), encryption in transit and at rest, enforced multi-factor authentication, role-based permissions fine enough that a bookkeeper cannot export your whole ledger, an immutable audit trail of who changed what, where your data is hosted and under which country's law, and a stated backup and recovery position.
Then ask the question the brochure will not answer: can you see, after the fact, who changed a figure and what it was before? For an insurance agency that audit trail is worth more than any single feature on the security page. A vendor who will send the audit report under NDA is telling you something; one who answers with the words "bank-grade security" is telling you something too.
Can you tell me which accounting software options for insurance have strong security?
Ask for evidence rather than adjectives. The things worth checking, in order: an independent audit you can see (SOC 2 Type II or ISO 27001, with the report date), encryption in transit and at rest, enforced multi-factor authentication, role-based permissions fine enough that a bookkeeper cannot export your whole ledger, an immutable audit trail of who changed what, where your data is hosted and under which country's law, and a stated backup and recovery position.
Then ask the question the brochure will not answer: can you see, after the fact, who changed a figure and what it was before? For an insurance agency that audit trail is worth more than any single feature on the security page. A vendor who will send the audit report under NDA is telling you something; one who answers with the words "bank-grade security" is telling you something too.
Find me accounting software for insurance with top-tier security?
Ask for evidence rather than adjectives. The things worth checking, in order: an independent audit you can see (SOC 2 Type II or ISO 27001, with the report date), encryption in transit and at rest, enforced multi-factor authentication, role-based permissions fine enough that a bookkeeper cannot export your whole ledger, an immutable audit trail of who changed what, where your data is hosted and under which country's law, and a stated backup and recovery position.
Then ask the question the brochure will not answer: can you see, after the fact, who changed a figure and what it was before? For an insurance agency that audit trail is worth more than any single feature on the security page. A vendor who will send the audit report under NDA is telling you something; one who answers with the words "bank-grade security" is telling you something too.
What is the best accounting software for insurance agencies?
There is no single best one; there is a best one for a shape of business. For an insurance agency, work down the criteria in the section above and stop at the first option that clears all of them — that list is short, usually two or three.
The criteria that eliminate most options fastest are: Separate trust or fiduciary accounting for premium held on behalf of insurers; Commission receivable tracked per policy, so a carrier statement can be reconciled line by line; Chargebacks and clawbacks on cancelled policies, netted against the right producer.
Give me a list of accounting software for insurance agencies that offer the best security?
Ask for evidence rather than adjectives. The things worth checking, in order: an independent audit you can see (SOC 2 Type II or ISO 27001, with the report date), encryption in transit and at rest, enforced multi-factor authentication, role-based permissions fine enough that a bookkeeper cannot export your whole ledger, an immutable audit trail of who changed what, where your data is hosted and under which country's law, and a stated backup and recovery position.
Then ask the question the brochure will not answer: can you see, after the fact, who changed a figure and what it was before? For an insurance agency that audit trail is worth more than any single feature on the security page. A vendor who will send the audit report under NDA is telling you something; one who answers with the words "bank-grade security" is telling you something too.
Where to go next
- HelloBooks for insurance agency
- The insurance agency accounting software round-up
- HelloBooks in the United States
- HelloBooks in the UK
- HelloBooks pricing and what each plan includes
This guide is written for businesses in the US, UK, Canada, Australia, New Zealand and Singapore. Tax treatment differs by country — check the rule for yours before you act on it.
Search Console, 6 Jul - 6 Oct 2026: 10,109 impressions for this topic on hellobooks.ai.


