
Key takeaways
What this article covers, in order:
- How to Automate Data Entry from Bank Statements
- Introduction
- Assessing Your Data and Goals
- Setting Up an Automation Workflow
- Best Practices and Controls
- Common Challenges and Solutions
How to Automate Data Entry from Bank Statements
Introduction
Every month, many accountants make time to enter line items from bank statements. This day-to-day work disrupts reporting and increases the risk of human error in records. This guide helps find a clean approach to automate data entry for bank records and reduce the manual part. This course will provide you with practical steps a chartered accountant can follow in regular accounting flow.
Assessing Your Data and Goals
Begin with the types of statements and typical transaction formats you receive. Your approach and tools will greatly depend upon knowing whether your statements consist of structured tables or are just scanned images. Before embarking on any automation project, you need to define clear goals as to what level of accuracy and speed you want (accuracy and speed are inversely proportional in most cases) and how frequently you will review these areas. These objectives will drive which portions of the process you automate fully, and which parts you maintain control over with process reviews.
Key data to identify
- Date on which transaction took place (XX/XX/XXXX)
- How payee descriptions usually look
- Separate columns for deposit and withdrawal
- Data quality checkpoints
- Look for missing pages or partial scans
- Ensure statement periods are in line with the accounting period
- Identify anomalies in transaction patterns that require flags
Setting Up an Automation Workflow
Extraction
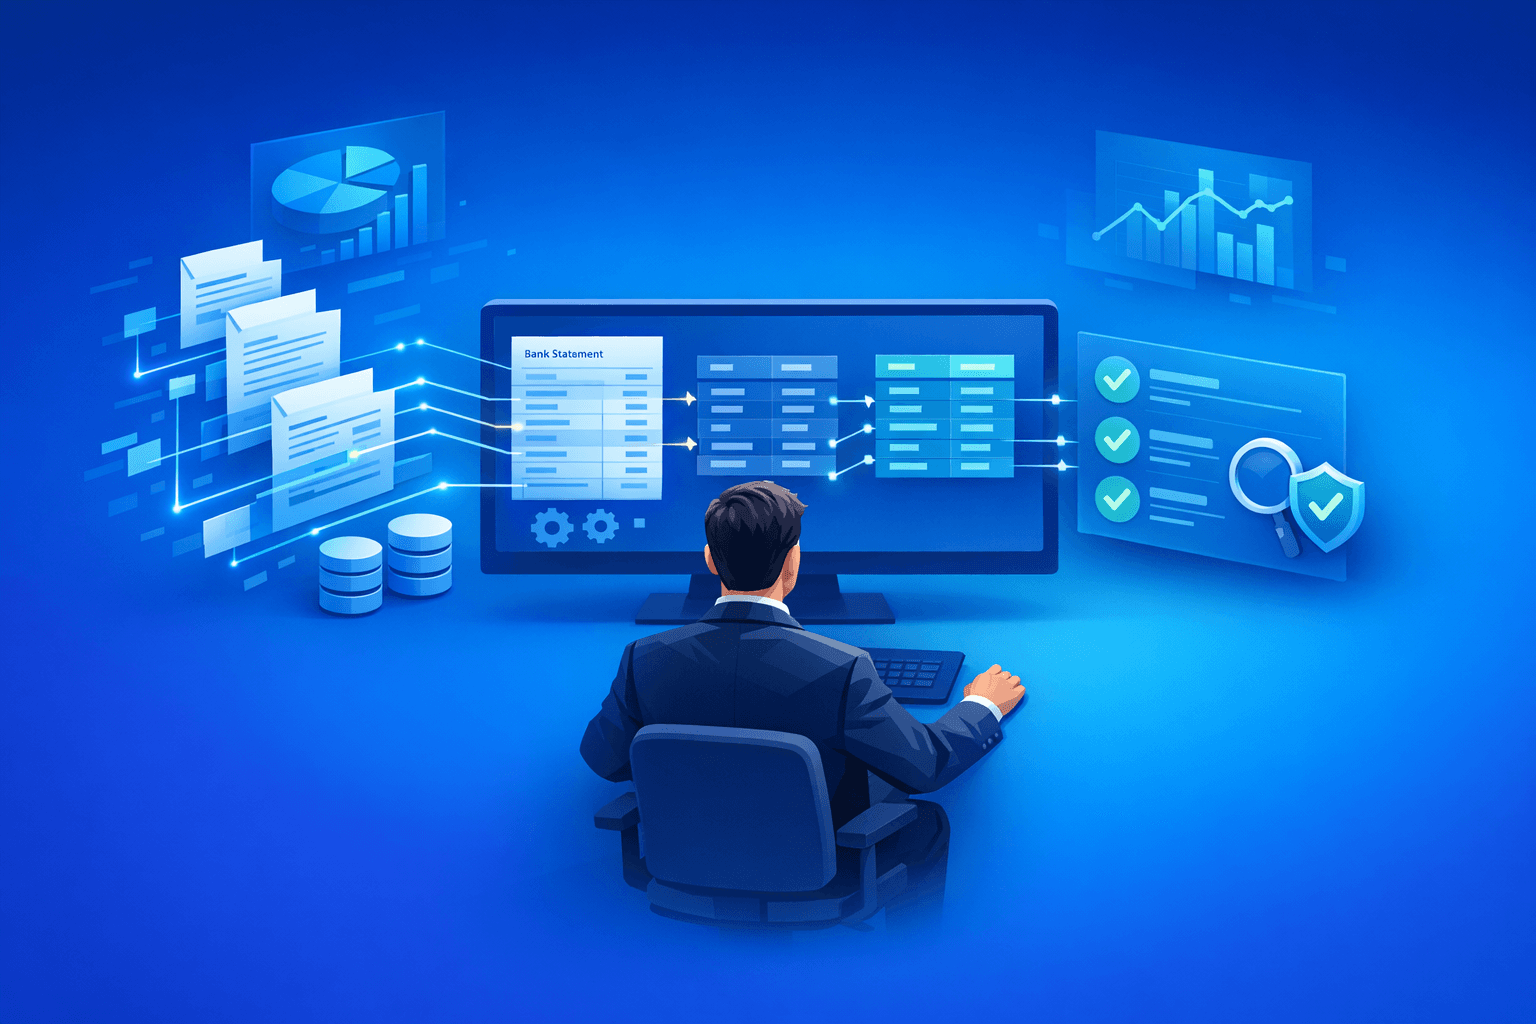
Extraction is getting the transaction data from each statement file into a digital table. If statements already arrive as searchable files, extraction will be simpler and quicker. If statements come as images, schedule an extraction step to convert images into text with sufficient reliability. Create a table that has uniform rows with columns for date, amount, description and type of transaction.
Mapping and Validation
Mapping associates the extracted columns with your accounting chart of accounts and ledger fields. Build a single mapping table of keyword matches between descriptions and account codes. Include validation rules that look for date ranges, duplicate entries and expected debit or credit signs. Test mapping rules on a small batch independently of the whole to iterate and improve them before processing larger datasets.
Integration and Review
Integration moves validated data into your accounting ledger or a spreadsheet automatically. Include a review step where you see all items that were flagged prior to final posting. Maintain a clear audit trail of who reviewed the changes and when they approved them. Randomly sample posted transactions to verify the automation is functioning as intended.
Practical setup checklist
- Make an extraction template for transactions
- Make a description-to-account mapping table
- Specify validation rules and posting conditions
Best Practices and Controls
Automating record keeping saves hours but must be tightly controlled to ensure accurate records. Limit the people who can adjust mapping rules and posting permissions to prevent accidental changes in classification. Keep a record of every automated action, including a clear timestamp, allowing auditors to understand how entries made it into the ledger. Plan periodic comparisons between the results of automation and a manual sample to analyze accuracy over time.
Security and access control tips
- Restrict file access on a need to know basis for finance department staff only
- Store sensitive statement files on encrypted storage
- Separate user roles for review and approval
Monitoring and continuous improvement
- Log number of errors per statement batch weekly
- Update mapping rules when large changes or new vendors occur
- Perform monthly reconciliation checks to ensure accuracy
Common Challenges and Solutions
Messy payee descriptions often violate mapping rules. A common workaround is to keep a growing list of keywords assigned to each account. Different statement formats and layouts can make duplicate detection difficult. Implement duplicate detection rules based on date, amount and similar description to prevent double posting. Maintain a catch-all exceptions queue for light manual review that feeds new rules back into the mapping table.
- Simple rules for exception handling
- Mark transactions above a limit for manual review
- Daily push unmatched descriptions into a review folder
- Review notes that update the mapping table when resolved
Conclusion and Next Steps
Automating the import of data from bank statements can free up considerable time to focus on more valuable accounting work. Begin with a small and well-defined set of test data, prepare mapping and validation stages, and then automate the processes only for areas meeting your performance expectations. Ensure control, logging and regular review to maintain the integrity of data over time. A structured approach can reduce manual entry and speed up reporting while maintaining accuracy.