Input-tax credit is a payment-time decision, not a filing-time report
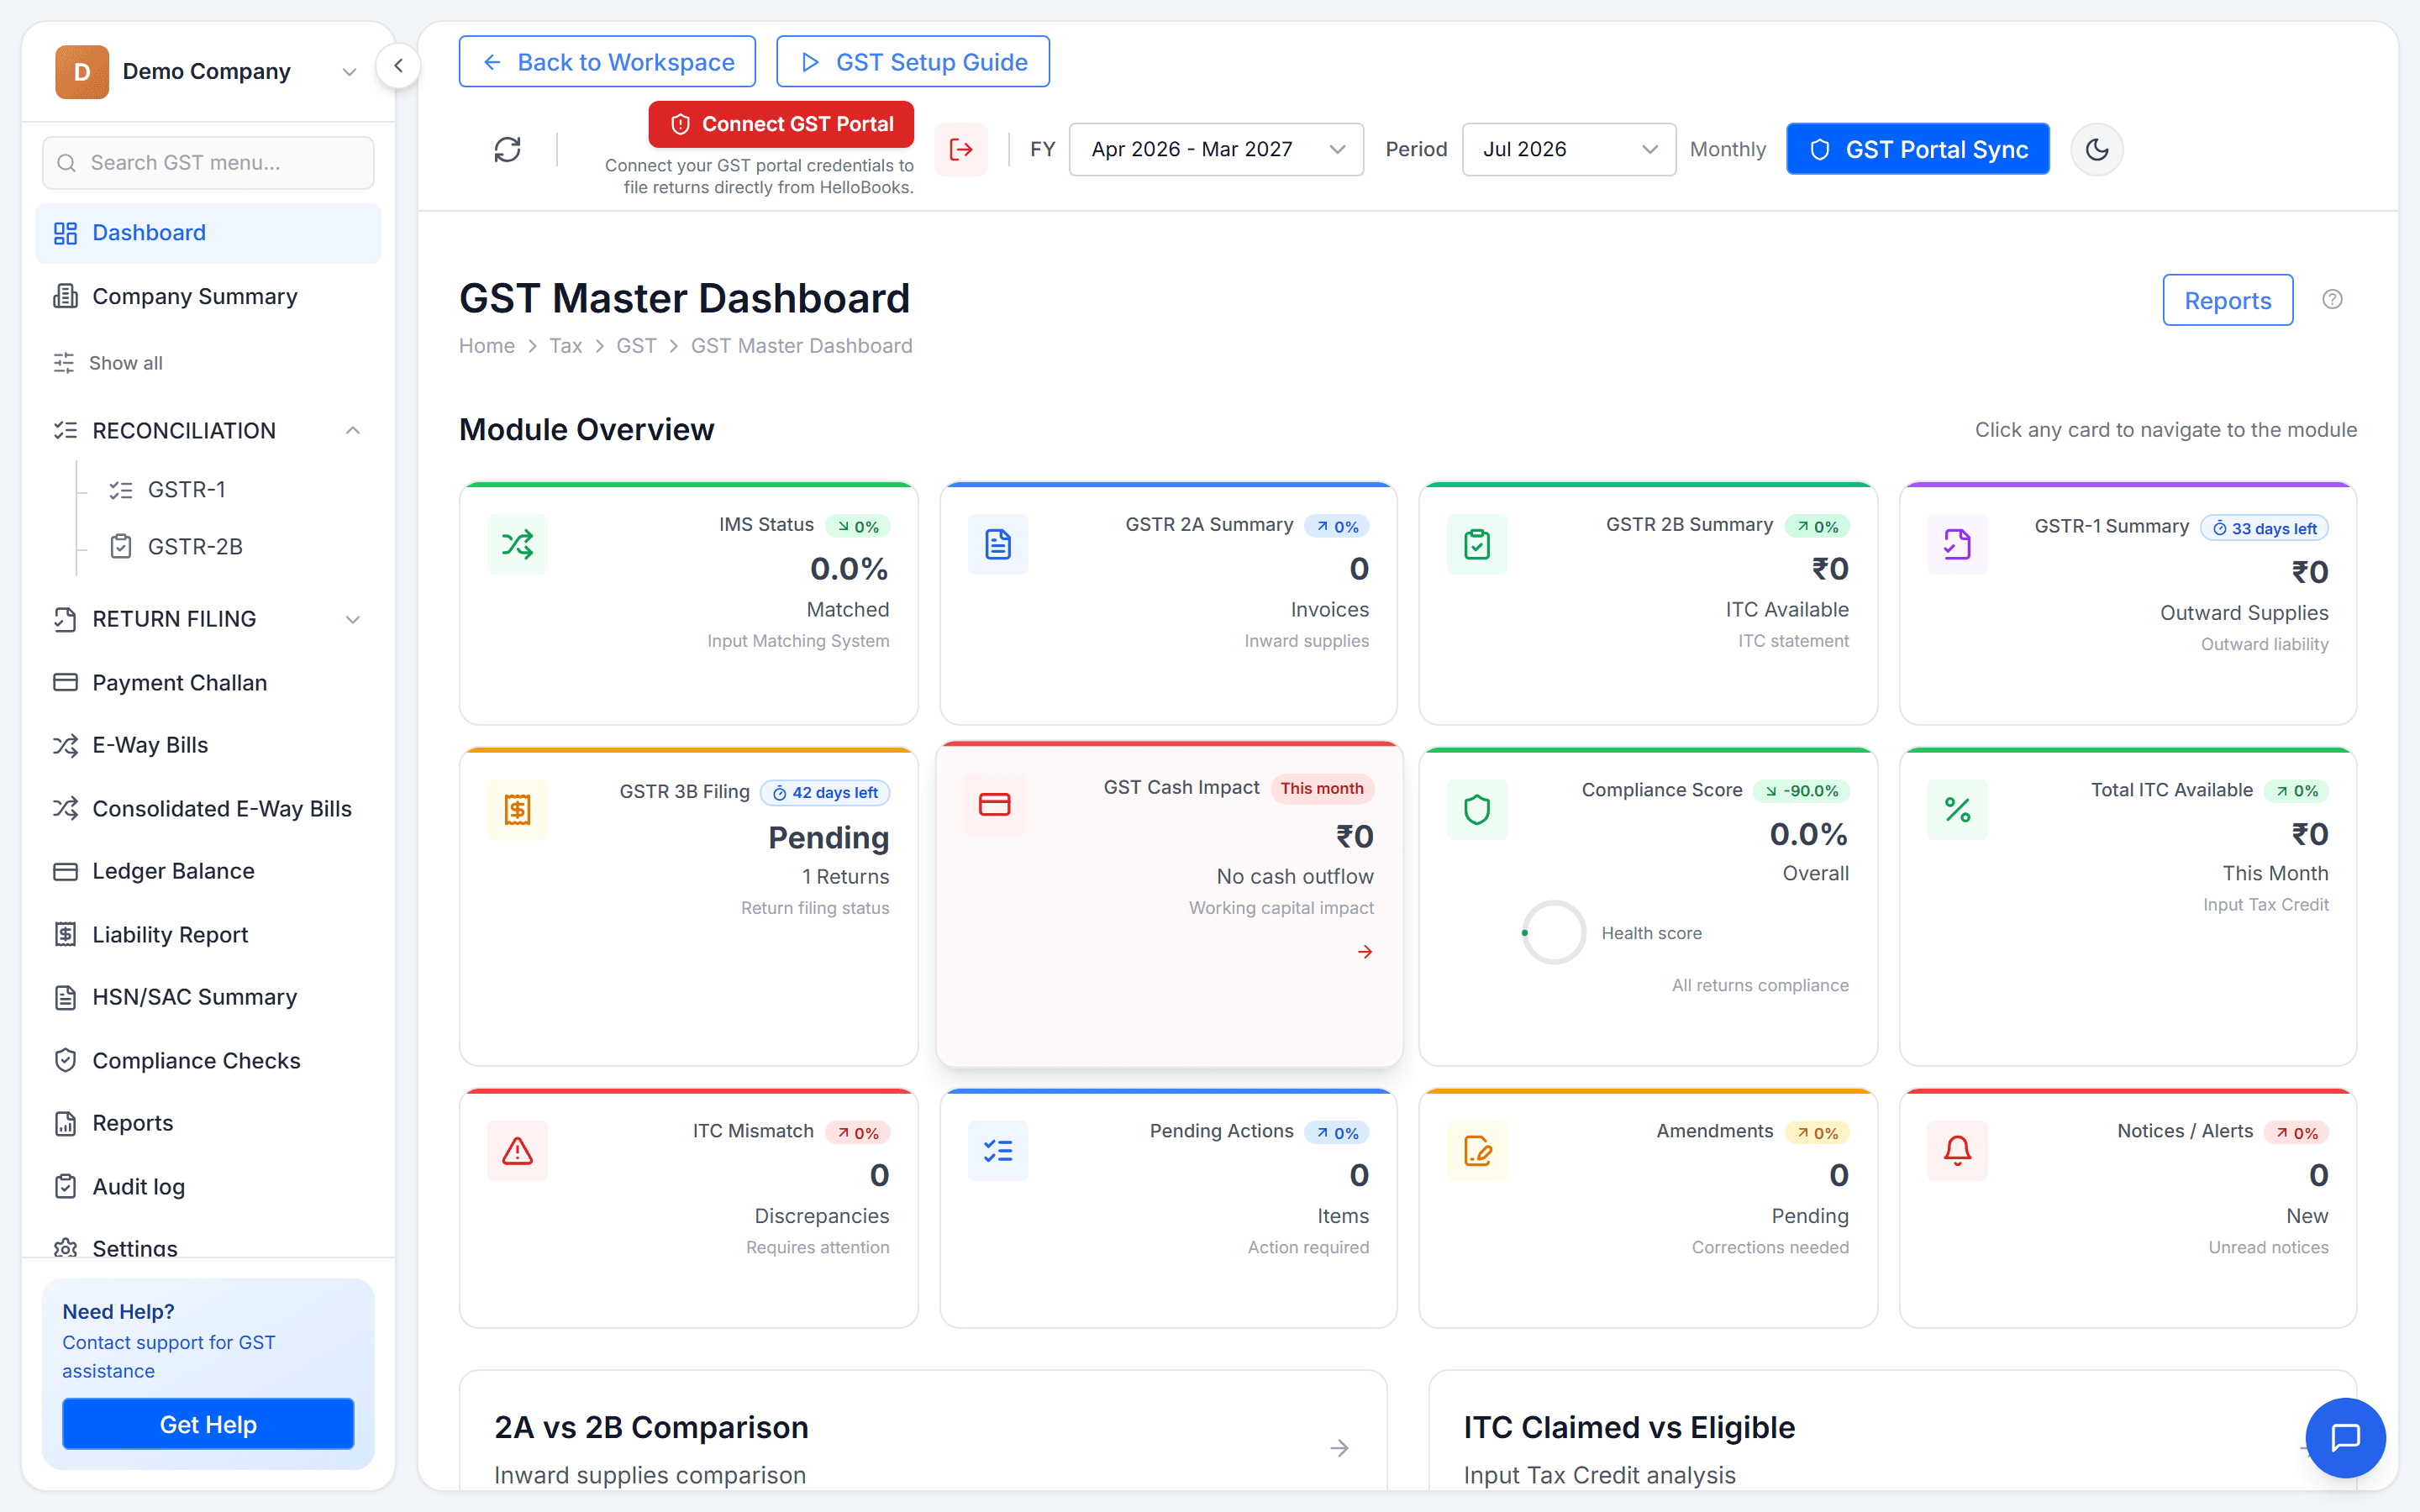
Most GST tools reconcile 2A/2B as part of preparing the return — you upload a purchase register at month-end, run the match, and get a report of what did and didn’t show up. By then the cash is often already out the door. If a vendor never filed their GSTR-1, the ITC you claimed against their invoice is at risk, and you find out weeks after you paid them.
HelloBooks moves that decision earlier. Because your bills and your 2A/2B reconciliation live in the same ledger, every payable carries a live signal — is this bill’s ITC in my 2B yet? — so the person about to release the payment sees the risk, not just the person filing the return three weeks later.
 Smarter accounting for growing businesses
Four ticks = claim.
- Step 1
Tax invoice
Invoice or debit note from a registered supplier
- Step 2
Goods received
For instalments, ITC arises on the last one
- Step 3
Shows in GSTR-2B
Proof the supplier reported the tax
- Step 4
GSTR-3B filed
You furnish the return for that period
- Step 5
Paid in 180 days
Otherwise reverse with interest, re-avail on payment
Proviso to 16(2)
Miss one and the credit is blocked or reversed.