Key takeaways
What this article covers, in order:
- Immediate savings and focusing on growth
- Smarter cash flow forecasting
- Scalability without proportionally higher costs
- Enhanced compliance and tax readiness
- Human oversight and decision augmentation
- The nuts and bolts of implementing AI bookkeeping
Why AI Bookkeeping Software Is a Must for Every Startup in 2026
The pragmatic reasons, real results and how-to for founders to implement AI bookkeeping platforms so financial processes become faster & more accurate.
Startups move fast. Founding teams are constantly stretched across product development, customer acquisition, hiring and fundraising just to keep the lights on. Manual data entry into spreadsheets combined with the need to reconcile accounts repeatedly are slow and error prone tasks. AI bookkeeping removes that burden from founders and small finance teams, providing speed, accuracy, and insight. This post discusses why AI bookkeeping is something every startup should consider implementing today and how to manage it effectively.
Immediate savings and focusing on growth
One of the most obvious advantages to AI bookkeeping is the amount of time it can save you. You can even automate your normal bookkeeping tasks such as invoicing, receipt categorization and bank reconciliation. That cuts down on time spent on administrative tasks and allows founders and finance leads to turn their attention to strategic activities such as planning cash flow, making pricing decisions and communicating with investors. “Even a few hours per week can have an impact on product development and customer outreach for a lean startup.
Improved accuracy and reduced risk
Manual bookkeeping means introducing human error: miscategorized expenses, missed invoices and reconciliation mismatches. AI bookkeeping leverages pattern recognition as well as ongoing learning to consistently classify transactions and identify anomalies. Startups diminish risk around misreported financials, late payments and compliance by reducing errors. Accurate records are also helpful in preparing for audits, investor due diligence and filing taxes.
Real-time financial visibility
Startups require accurate, current financial information to act quickly. That means AI-based bookkeeping systems are capable of real-time data crunching, giving you almost real-time ledgers and dashboards. Founders are able to control cash runway, recurring revenue trends and expense spikes as they occur, instead of waiting for monthly closings. This pace of insight supports premptive decisions such as reducing sales spend, recalibrating hiring plans, or ramping up sales efforts when necessary.
Smarter cash flow forecasting
Cash flow is what keeps a startup alive and allows it to scale. With AI bookkeeping, forecasting becomes much more intelligent by examining historical trends, seasonal numbers, client payment behaviors and regular outgoings. Automated forecasting is useful for predicting cash runway in various scenarios and providing a recommendation as to the timing of a funding round or when cost should be reduced. Startups that embrace the use of AI-powered projections are better able to steer clear of cash crunches and confidently deploy their investments.
Streamlined expense management and controls
It is easier to manage expense when data in receipts are automatically captured by AI and expense is categorized. Startups are able to establish policies for approvals, flag weird vendor activity and keep consistent policies across teams. AI also facilitates the enforcement of policies by identifying non-compliant purchases and alerting approvers. Tighter controls minimize the risk of fraud and help ensure that company money is used as intended.
Faster, cheaper month-end close
Month-end close is onerous for small teams. AI-powered bookkeeping speeds up reconciliation and reduces the back and forth that often goes along with clearing discrepancies. Bank transactions are automatically matched to invoices and receipts, which cuts down the close cycle as well as the requirement of hiring temporary help or external accountants during month-end. The result: a predictable and timely closing of the books and more informed decision-making.
Scalability without proportionally higher costs
Where revenues and transaction volumes are increasing, manual bookkeeping frequently results in workforce expansion. AI accounting scales differently: It processes greater transaction volume with only a low marginal cost. This allows startups to keep a lean finance team while still providing for growth. The scalability benefit keeps opex contained and unit economics expanding as the company grows.
More readiness for fundraising and due diligence.
"Access to capital today is demanding for clean, organized and certifiable financials. AI bookkeeping delivers conformity standardized and thoroughly categorised financial statements and their associated transaction trails. “With accurate historicals, proper revenue recognition and reliable cash forecasts, fundraising discussions can be far more productive and credibility higher.”
Enhanced compliance and tax readiness
The tax laws and filings can change often. Doing your small-business bookkeeping using AI keeps accurate records to streamline taxes. Up-to-date ledgers and categorized expenses will help tax specialists work faster, with fewer surprises. Penalties are lighter, deductions clearer and tax outcomes more predictable for startups.
Human oversight and decision augmentation
Artificial intelligence bookkeeping isn’t an alternative to human judgment — it’s an amplifier. Tactical perseverance with strategic overlays will underpin the survival of entrepreneurial human finances: Monotonous tasks and emergent issues are relegated for the attention of automated systems, as finance professionals apply context and strategy. This partnership raises quality: AI squelches noise, and humans focus on exceptions, strategic interpretation and relationship management with banks, vendors and investors.
The nuts and bolts of implementing AI bookkeeping
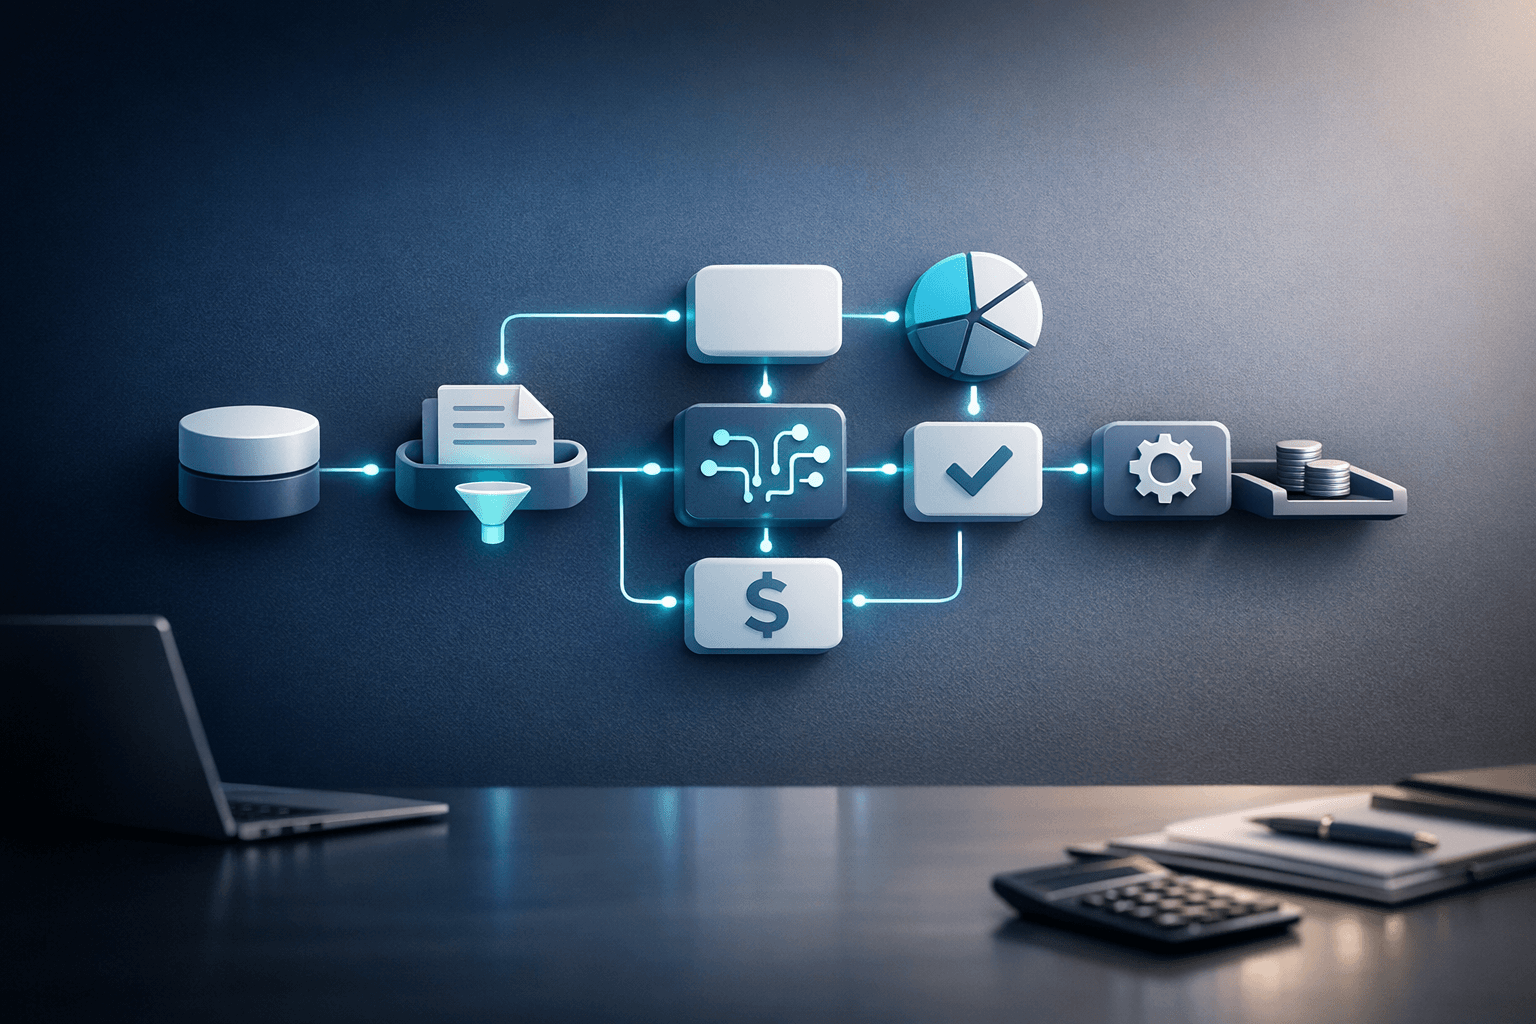
Define what you want to automate: Start with a clear objective of what business process do you want to automate-reconciliation, expense capture, invoicing or reporting. Prioritize the most time-consuming tasks.
Clean historical data : A short data-cleanup pass clears friction from the onboarding process to get AI learning faster.
Seamlessly integrate with core financial feeds: Make sure bank and payment data moves easily and securely for accurate reconciliation.
Create rule sets and review cycles: Define approval workflows, categorization rules, and a release cycle for human review of exceptions.
Train the team: Spend time teaching founders and finance staff how to review AI suggestions and what to do with items that are flagged, as well as how to understand new dashboards.
Monitor and iterate: Measure accuracy, time saved, and financial KPIs while honing automation rules over time.
Some mistakes and how not to make them
Too much automation, without control: For or against category: Balance it with approval gates to avoid misclassification.
Ignoring integrations: Select a system that can work with your bank feeds and invoicing, so you don’t have to perform manual exports.
Ignoring security: Use strong access controls and encryption to secure financial information.
Not having a human in the loop: Set reminders to periodically verify that your AI models are still accurate as your business changes.
Conclusion
AI bookkeeping is a useful, life-changing service for startups. By automating data entry, increasing accuracy and providing real-time financial information, AI powered bookkeeping solutions free up founders to focus on growing the business while reducing risk amond most common errors that the young firm makes, and can lay a strong foundation future fundraising and compliance. For startups who want to move quickly, see clearly and scale hard, AI bookkeeping today isn’t just a convenience…it’s a competitive advantage.