
Key takeaways
What this article covers, in order:
- Cash Flow Statement Explained for Small Business Owners
- A plain-English guide to understanding, building, and using your cash flow statement
- A simple way to think about cash flow
- Quick checklist: Do you need to focus on cash flow?
- What is a cash flow statement?
- Why it matters to small businesses
Cash Flow Statement Explained for Small Business Owners
A plain-English guide to understanding, building, and using your cash flow statement
Profit and cash are not the same thing. A business can look profitable on paper and still go broke if cash runs out. Your cash flow statement shows where money actually came from and where it went. Read it monthly. It's the report that keeps the lights on.
A simple way to think about cash flow
A lot of small business owners treat profit and cash as the same thing. They aren't. You can be profitable on paper and still miss payroll. The cash flow statement is the report that catches this gap.
It shows how money moved into and out of your business in a given period. Once you understand it, you can spot shortfalls early. You can plan investments. You can keep the doors open.
Quick checklist: Do you need to focus on cash flow?
You probably do if any of these sound familiar:
- You've felt "profitable but broke."
- You've been surprised by a slow month.
- You don't know your runway in days or weeks.
- You've borrowed to make payroll more than once.
- You can't tell a lender what your next 90 days look like.
If you nodded, keep reading.
What is a cash flow statement?
The cash flow statement summarizes every dollar that came in and every dollar that went out — grouped into a few clear buckets. Your income statement shows what you earned and spent on paper.
Your cash flow statement shows what actually hit the bank. It answers one simple question: where did the cash come from, and where did it go?
Why it matters to small businesses
Cash is the lifeblood. Bills, payroll, supplier payments, and emergency reserves all need to line up at the right time.
A clear cash flow statement helps you:
- Spot when money will be tight.
- Make smart calls on hiring, inventory, and big purchases.
- Show lenders or investors that the business is healthy.
- Plan with real numbers, not just profit on paper.
The three core parts
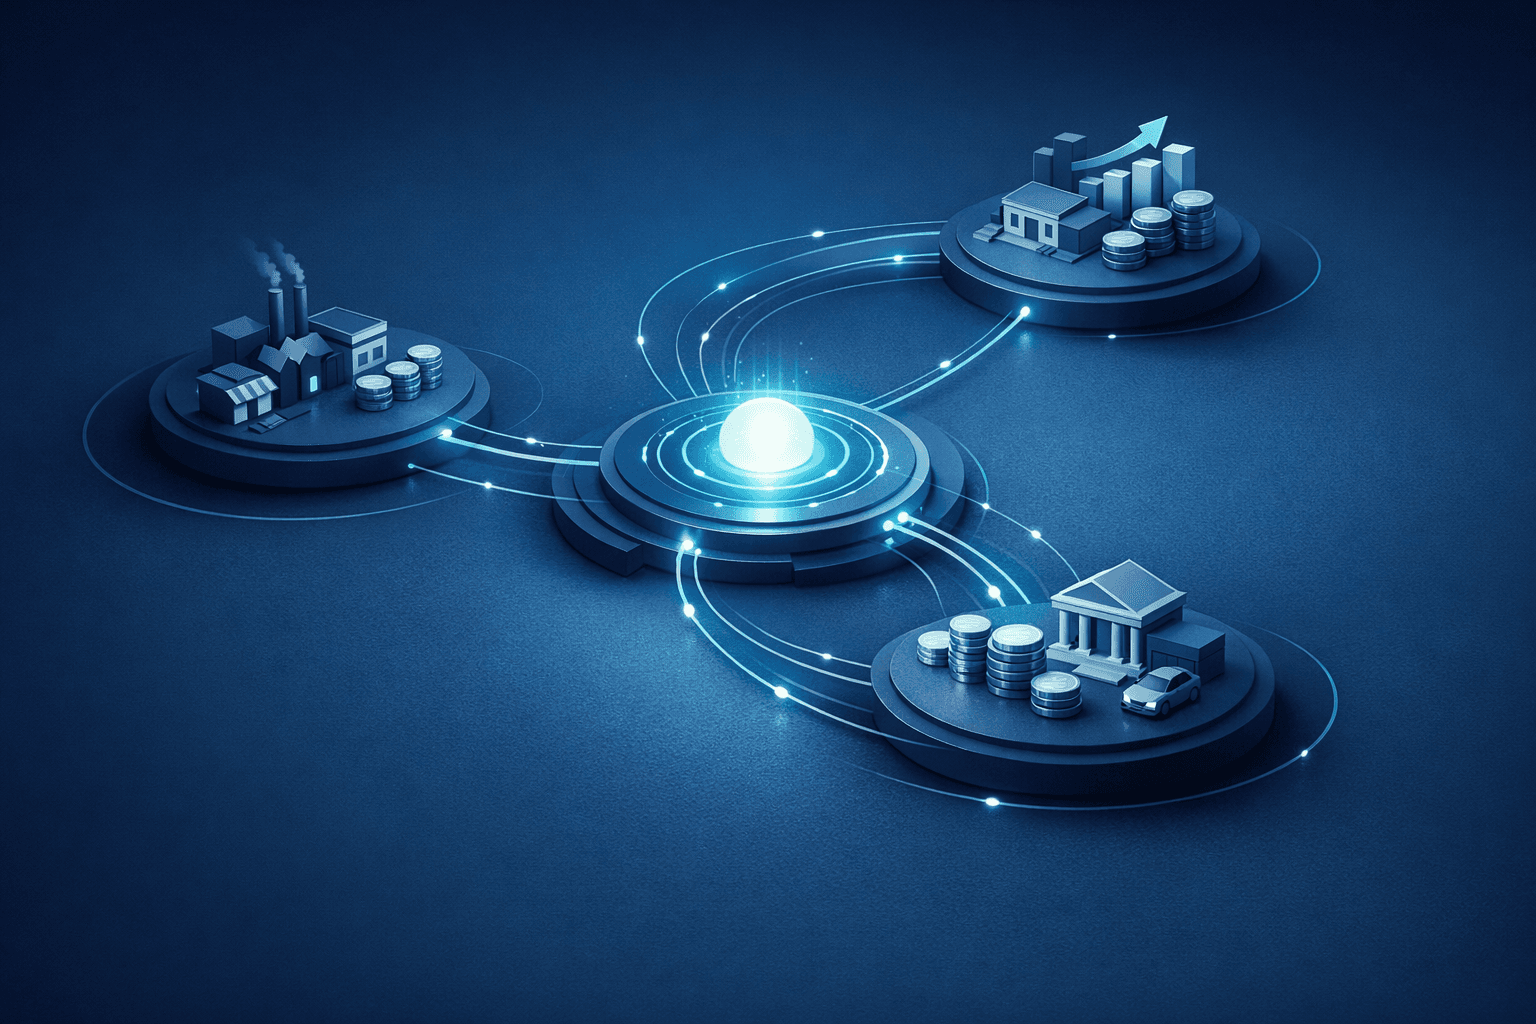
Every cash flow statement has three sections. Knowing what each one means is half the battle.
Operating activities
This is your day-to-day business. Money in from customers. Money out to suppliers, staff, and rent. It's the cleanest view of whether your core business actually generates cash.
Investing activities
This is what you spend or earn on long-term assets. Buying equipment. Selling a vehicle. Picking up new property. A big outflow here can be smart — but only if you've got the cash to cover it.
Financing activities
This is the money side of the business. Loans coming in. Loans going out. Owner contributions and dividends. If you're constantly borrowing to cover operations, this section will show it.
Two ways to prepare it
There are two methods. Most small businesses use the second one.
Direct method
You list actual cash receipts and payments — cash from customers, cash to suppliers, and so on. It's clear and detailed. But it takes more work.
Indirect method
You start with net income, then add back non-cash items like depreciation. You also adjust for changes in receivables, inventory, and payables.
Most small businesses pick this method. It ties your income statement and balance sheet together neatly.
How to actually read your statement
Don't just glance at the totals. Look at the relationships.
Positive operating cash flow means your core business is paying for itself. That's the goal.
Negative operating cash flow, month after month, is a warning sign. You may need to cut costs, raise prices, or rethink the model.
Big investing outflows can be smart bets — new equipment or property — but only if you can absorb the timing without going short on cash.
Frequent financing inflows to cover payroll? That's a red flag. Borrowing to keep the lights on isn't a strategy.
A few simple performance measures
You don't need a finance degree to use cash flow data well. A few simple measures go a long way.
Operating cash flow vs. net income: Are your profits actually showing up as cash? If not, find out why.
Free cash flow: Operating cash flow minus capital spending. That's the cash you can use for debt, dividends, or reinvestment.
Cash burn rate: For startups or seasonal businesses, this tells you how fast cash is draining — and how many months of runway you've got left.
Forecasting your cash flow
The single best habit you can build is a rolling cash flow forecast. Start with the next 12 months. Project what you expect to bring in and pay out each month.
Build it as a driver-based model:
- Tie sales forecasts to billing schedules.
- Layer in your accounts receivable aging.
- Use your average collection period.
- Factor in inventory turnover.
Add scenario planning. What if customers pay late? What if a big order falls through? What if a supplier hikes prices?
Each scenario should have a clear plan attached. Don't let the forecast go stale. Update it every month with actuals. Note the variances. Adjust your assumptions.
A few forecasting habits that work:
- Run rolling forecasts that show opening cash, inflows, outflows, and ending balance month by month.
- Use best-case, base-case, and worst-case versions.
- Run sensitivity tests on collection rates and payment timing.
- Build a waterfall view that highlights any month with a negative ending balance.
Smoothing out seasonal swings
Seasonal businesses often look healthy over a year but feel broke for half of it. The fix is planning, not panic.
Spread your big costs across the year. Time major spending to land in months with strong inflows.
In lean months, talk to vendors. Many will accept partial orders, smaller POs, or consignment inventory.
Layer in financing only when you actually need it:
- A small revolving line of credit.
- Seasonal merchant facilities.
- Short-term invoice financing for known slow periods.
Look for ways to even out income. Off-season products. Service contracts. Prepaid sales.
Stagger payroll dates if it helps. Set aside a slice of peak-month profits in a reserve account.
Sell ahead of time. Prepaid packages. Discounted monthly subscriptions.
Pull future demand forward with smart promotions during slow months — just watch your margins and capacity.
Schedule big capital projects for off-peak periods. Or finance them so the cash hit doesn't land in your weakest month.
Smart use of payment terms
Your payment terms shape your cash flow as much as your sales do. Offer payment options that fit your customers but protect your cash. Card and ACH usually settle fastest.
Use dynamic discounting. A small early-payment discount can speed up cash and is often worth the trade.
For predictable revenue, use subscription billing or retainers. For big projects, use staged invoicing. Get a deposit. Bill at milestones. Don't wait for one big invoice at the end.
Other moves that help:
- Offer multiple payment channels — bank transfer, card, mobile wallet.
- Set clear early-payment discount terms with a hard due date.
- Use auto-reconciliation tools to match bank deposits to invoices.
- Ask new or high-risk clients for a deposit.
- Run credit checks on big new accounts.
Practical ways to generate more cash
Most cash flow wins come from a mix of operational tweaks and tighter financial controls.
Tighten collections: Bill on time. Shorten terms where you can. Chase overdue accounts politely but firmly.
Manage inventory: Don't overstock. Order more often in smaller batches. That frees up cash sitting on the shelf.
Negotiate with suppliers: Ask for longer terms. Or take an early-payment discount when it makes sense.
Audit your expenses: Recurring software, subscriptions, and services tend to creep. Cut or renegotiate the ones you don't need.
Time big purchases: Schedule large capital spending for months with strong inflows. Or finance it across the asset's useful life.
Common mistakes to avoid
A few traps catch most small business owners. Watch for these.
- Mistaking profit for cash: A profitable invoice that isn't paid doesn't help you make payroll.
- Ignoring your operating cycle: A great quarter can hide a bad off-season. Track the full cycle, not just the best months.
- Leaning too hard on credit: Short-term borrowing solves a moment. It also adds long-term cost and dependence.
- Skipping reviews: A cash flow statement is a planning tool. Read it monthly. At minimum, every quarter.
Putting your statement to work
Start simple. Build a basic monthly cash flow statement. Pull your historical receipts and payments. Use them as a baseline. Project expected inflows and outflows for the next 3 to 12 months.
Update it every month with new numbers. This living document tells you when to run payroll, when to make a big purchase, and when you can skip financing entirely.
Short-term financing options
Sometimes you need a cash bridge. The trick is matching the financing to the actual need. Long-term loans are overkill for short-term gaps. Expensive advances can eat your margins.
A few options to know:
- Revolving lines of credit are flexible. You only pay interest on what you draw, and you can reborrow as cash comes in.
- Invoice factoring turns receivables into instant cash but at a cost. Compare net proceeds against the liquidity gain.
- Invoice discounting lets you borrow against eligible invoices while still managing the customer relationship yourself.
- Merchant cash advances are fast but often expensive. Always check the APR.
- Supplier finance programs let a third party pay your suppliers quickly while you pay the financier on extended terms.
- Bank overdraft facilities handle short mismatches. Watch the fees and any covenants.
Using technology to automate cash management
Automation cuts errors and shortens the gap between invoice and bank deposit. Connect your accounting software to your bank feeds, payment processors, and point-of-sale systems.
Set up automated invoicing for recurring charges. Add one-click payment links so customers can pay in seconds. Use bank reconciliation tools that match payments to invoices automatically. Flag exceptions for review. Watch your DSO drop.
Build dashboards that track:
- Real-time cash balance.
- Forecast vs. actual variance.
- Alert thresholds before a trend gets ugly.
A few specific tools that pay off:
- Bank feed automation that downloads transactions, classifies them, and updates cash daily.
- Payment portals with instant card and ACH collection that post straight to your ledger.
- Automated reminder engines that send staged messages, attach pay links, and escalate overdue notices.
- Scenario dashboards that recalculate forecasts when you change sales speed, margins, or payment timing.
- AP automation that times supplier payments to optimize days payable outstanding while catching early-pay discounts when they're worth it.
The bottom line
A cash flow statement gives you confidence in your decisions. It cuts through the noise. When you split cash flow into operating, investing, and financing activities, you see the real picture of liquidity and sustainability.
Manage collections, inventory, and expenses with that picture in mind, and your business stays nimble. That's how you stay ready for growth instead of stuck reacting to surprises.